Disruption fears look overdone – trusted data, regulation and embedded workflows should continue to support resilient information services credits.
Generative and agentic artificial intelligence (AI) has been treated as an existential threat to established information services (IS) companies. We believe that risk is over-discounted. For issuers that own proprietary content, operate in regulated markets and sit inside mission-critical workflows, AI is more likely to improve products, extend distribution and support margins than destroy the franchise. The key distinction is between businesses that control trusted data and accountable outcomes, and those that provide a replaceable interface.
Equity valuations have absorbed more disruption risk than current credit fundamentals appear to justify. Bond market reactions have been more measured: stable earnings, strong cash generation and generally conservative balance sheets have limited fundamental stress, although longer-dated bonds remain more exposed to uncertainty around the terminal value of data and workflow franchises.
Figure 1: Strong balance sheets supported by consistent financial policies can absorb the impact of potential tech-related AI changes
IS companies’ current market cap and net adjusted leverage
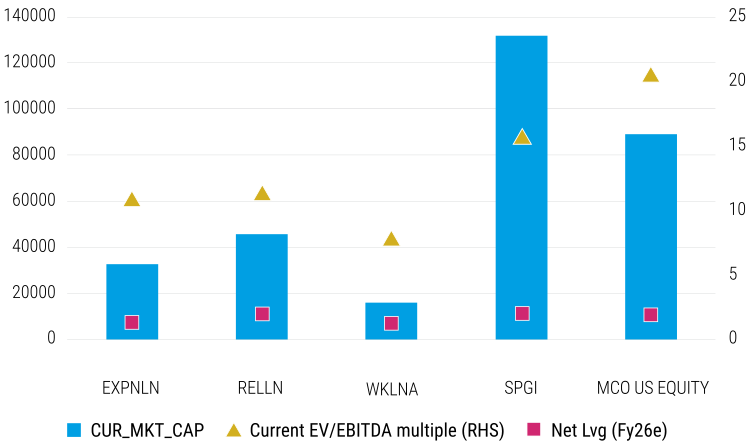
Source: Bloomberg and analysis of company reports, 4 September 2026
Figure 2: Spreads over 12 months have outperformed the index with underperformance modest YTD
OAS spreads of comparative IS € issuers compared to the € IG index
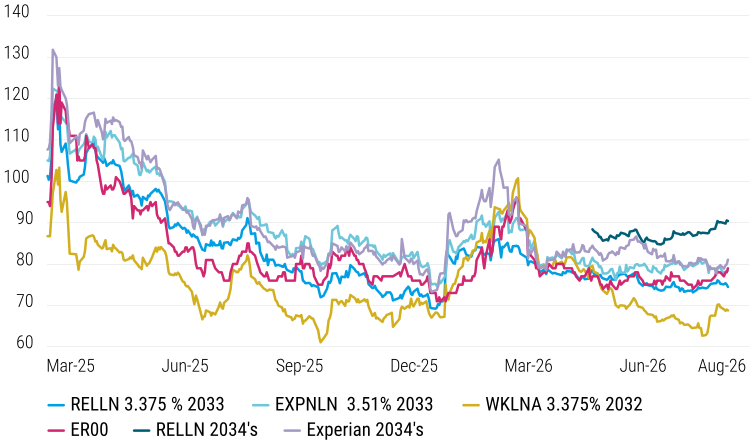
Source: Bloomberg, August 2026
Why the strongest businesses should remain resilient
1. Proprietary data ownership and quality
AI raises the value of clean, current and authoritative data because model output is only as reliable as the information on which it is grounded. IS companies have spent decades collecting, validating and enriching datasets that are difficult to replicate. Customers pay for accuracy, auditability, permissioning and expert curation. Recent results support this thesis: Experian reported 8% organic growth in FY26 and nearly $2 billion of revenue from new and scaling products2 ; RELX reported 7% underlying revenue growth and 9% underlying adjusted operating-profit growth in H1 20263 ; and Moody’s Q2 2026 revenue rose 15%, with Moody’s Analytics annualised recurring revenue up 9%.4
2. Business quality supports credit quality
Leading issuers typically combine recurring revenue, high renewal rates, strong margins and robust free cash flow. These traits matter because AI adoption requires sustained investment in cloud infrastructure, data engineering, model governance, cybersecurity and specialist talent. Scale lets incumbents fund that investment while protecting debt service and strategic flexibility. Strong cash flow generation and balance-sheet headroom help absorb higher technology spending and operational costs and, in a worst-case scenario, can manage operational incidents and associated costs. Smaller competitors face a tougher trade-off: underinvest and risk product erosion, or invest heavily and potentially weaken leverage and ratings.
3. Regulatory protection, accreditation and accountability
Rating agencies and credit bureaux operate in markets where regulation, accreditation and institutional trust create formidable barriers to entry. In high-stakes applications such as ratings, lending, legal research, tax, healthcare and compliance, customers require transparent methodologies, explainable decisions, permissioned data and an accountable provider. General-purpose models can improve the user experience, but they do not automatically inherit regulatory status, contractual liability or customer trust.
4. Mission-critical workflow entrenchment
The strongest platforms are embedded in customer processes rather than used as stand-alone databases. Their data feeds, analytics, decision rules and audit trails sit inside legal, financial, clinical and corporate systems, making replacement costly and risky. AI may change the interface, but the more likely base case is broader use of incumbent data and decision infrastructure, not wholesale displacement.
What could go wrong?
Agentic AI could move further up the workflow stack. Autonomous tools could execute complex tasks across multiple data sources at lower cost, reducing the value of incumbent interfaces. The risk is greatest where products support low-complexity decisions, rely on widely available information or have limited switching costs. Workflow-heavy providers such as Wolters Kluwer are more exposed than businesses whose moat rests on proprietary data, regulated status or authoritative content.
Cyber/data risks and reputational damage could overwhelm the benefit. More connected platforms, third-party models and cloud infrastructure expand the attack surface. For data-rich companies, a major breach could bring remediation costs, litigation, regulatory penalties, weaker new-business wins and lasting reputational damage. This is the most credible route from an AI-related event to material spread widening or rating pressure.
Execution and capital allocation could disappoint. Incumbents may underinvest, choose the wrong partners, fail to protect intellectual property or spend heavily without achieving adoption. Management teams could also respond to equity-market pressure with larger buybacks, debt-funded acquisitions or expensive AI capability purchases. RELX, for example, reported a £2.25 billion 2026 buyback programme given its low leverage (H1 2026 2.3x). These risks remain manageable while financial policies are disciplined, but can erode the balance-sheet advantage underpinning the credit case.
The bottom line: Implications for Investment Grade bonds
IS should be viewed as selective AI winners at the margin, not a uniform set of disruption losers. AI makes trusted, governable and workflow-ready data more valuable. The best-positioned incumbents own proprietary content, operate under meaningful regulation, deliver accountable outcomes and retain the capacity to invest. Credit investors should focus on who owns the data, who carries the liability, how deeply the product is embedded, and whether the balance sheet can withstand execution, cyber and capital-allocation shocks.
Within investment grade bonds, AI is more likely to create issuer dispersion and episodic volatility than broad-based fundamental deterioration. Stronger credits should benefit from recurring cash flow, margin resilience and manageable leverage, but tight spreads limit broad upside. Headline-driven selloffs can create opportunities where a severe disruption scenario is not visible in operating performance.
We view most sector valuations as broadly fair, with Experian offering the better risk-reward because its difficult-to-replicate datasets and trust and accountability requirements make it more likely to be an AI enabler than a casualty. The principal downside risk remains a major cyber incident, but we view this as a tail risk that would be workable for a strong active management team.