GB
gb
GB
en-GB
gb_inst_classes
inst
Institutional
en
en
Insights

Unlocking value in Japanese equities

Japan’s companies are adopting more shareholder friendly policies. We explore the opportunities for investors and explain why we’re currently overweight Japanese equities across the CT Universal MAP portfolios.

The chart shows that Japanese companies are enjoying good profitability, but, much more importantly, that these companies are rapidly increasing their use of buy-back plans as part of a shift to deliver greater returns to shareholders.

Japanese companies start to focus on shareholder value

TOPIX aggregate net income and share buyback announcements
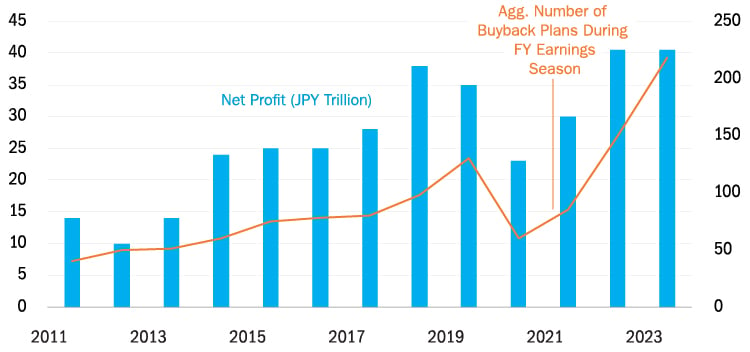
Japanese companies start to focus on shareholder value
Source: Columbia Threadneedle Investments, BofA Global Research, QUICK and J.P Morgan Asset Management as at 27 2023. Based on TOPIX companies with fiscal year ending in March. Share buybacks aggregated from April 1st  to May 18th for each year.

There’s often been talk of Japanese companies adopting more shareholder friendly policies, but this time it is the law!

In April of this year, another policy move aimed at increasing Japanese corporate profitability was launched, the inelegantly named Action Plan for Substantiation of Corporate Governance Reform. Companies listed on the Tokyo Stock Exchange are required to disclose risk-taking plans and measures taken to achieve growth while keeping profitability in mind. More specifically, firms with a price-to-book (P/B) ratio below 1x will be flagged and requested to “properly identify” their cost and efficiency of capital.

Our global equity team have flagged that the magnitude of cash on some Japanese firms’ balance sheets provides clear opportunities to increase return on equity by around 5%. That means handing the zero-yield cash back to investors and even considering gearing up their balance sheets with borrowing at current low rates. This represents a very significant opportunity for companies to boost to shareholder returns and one that can be independently delivered by the management and which is not reliant on any external market or economic factors.

Valuations still look attractive in the region especially with the structural changes that are occurring within Japanese corporates. Increased research & development and investment should translate to productivity gains and buybacks and dividend payments have been increased, which should mean better shareholder returns. Central bank monetary policy remains incredibly loose.  We are currently overweight Japanese equities.
17 October 2023
Keith Balmer
Keith Balmer
Portfolio Manager, Multi-Asset Solutions (EMEA)
Key topics
Related topics
Listen on Stitcher badge
Key topics
Related topics

Risk Disclaimer

The value of investments and any income derived from them can go down as well as up as a result of market or currency movements and investors may not get back the original amount invested.

Views and opinions expressed by individual authors do not necessarily represent those of Columbia Threadneedle Investments.

Past performance should not be seen as an indication of future performance.

Related Insights

21 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: The roadmap for central banks

After a series of policy meetings across the major central banks, the direction of travel for interest rates remains finely balanced.
14 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: Why does the Fed have to hike rates?

Central bank policy is back at the forefront of investor attention as inflation data challenges expectations of an imminent easing cycle.
8 September 2026

Senior Economist, Multi-Asset Solutions team

Delegate OCIO & Strategist

Multi-Asset Investment Outlook 2027: Technological tailwind, geopolitical headwind

The global economy has proved more resilient than many expected, but the investment landscape of 2027 looks materially different from a year ago – shaped by conflict in the Middle East, a reversal in interest rate expectations, and an AI-driven capital expenditure (capex) boom of unprecedented scale.
22 September 2026

In Credit Weekly Snapshot – Encore une fois

The spread between French and German government debt has once again breached 100bps, reflecting a confluence of French fiscal and political pressures.
21 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: The roadmap for central banks

After a series of policy meetings across the major central banks, the direction of travel for interest rates remains finely balanced.
17 September 2026

Senior Portfolio Manager, Investment Grade Credit

Hyperscaler debt issuance: A technical opportunity in investment grade credit

AI hyperscalers are reshaping the IG credit market, creating attractive dislocations in fundamentally strong issuers – and an attractive entry point.
true
true

Risk Disclaimer

The value of investments and any income derived from them can go down as well as up as a result of market or currency movements and investors may not get back the original amount invested.

Views and opinions expressed by individual authors do not necessarily represent those of Columbia Threadneedle Investments.

Past performance should not be seen as an indication of future performance.

You may also like

Investment approach

Teamwork defines us and is fundamental to our investment approach, which is structured to facilitate the generation, assessment and implementation of good, strong investment ideas for our portfolios.

Funds and Prices

Columbia Threadneedle Investments has a comprehensive range of investment funds catering for a broad range of objectives.

Investment Strategies

We offer a broad range of actively managed investment strategies and solutions covering global, regional and domestic markets and asset classes.
Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.