GB
gb
GB
en-GB
gb_inst_classes
inst
Institutional
en
en
Insights

Multi-asset GMAI update: sticking to the process

We are living and investing in a very uncertain and constantly changing environment. Any views we put on paper can be redundant within a day or two as we see yet another set of extraordinary measures from governments and central banks to support the economy and businesses to get through this awful period and return to some level of normality. However, you as investors still want to be updated as frequently as possible and our aim as a multi-asset team and firm is to ensure we keep you abreast of what we are doing in the portfolio as often as possible, without overload.
As investors many of you are aware that we have had very little duration in the Threadneedle Global Multi Asset Income Fund portfolio for a number of years now, rather investing our “dry powder” in light-duration assets such as short-term UK government bonds, cash and short-dated UK investment grade credit in the belief that these offer better protection than long-dated fixed income. The duration we have held has mainly been focused in US Treasury Inflation-Protected Securities (TIPS), where we have opportunistically taken allocations; firstly back in 2015, before exiting in early 2016, and re-entering in December 2016.
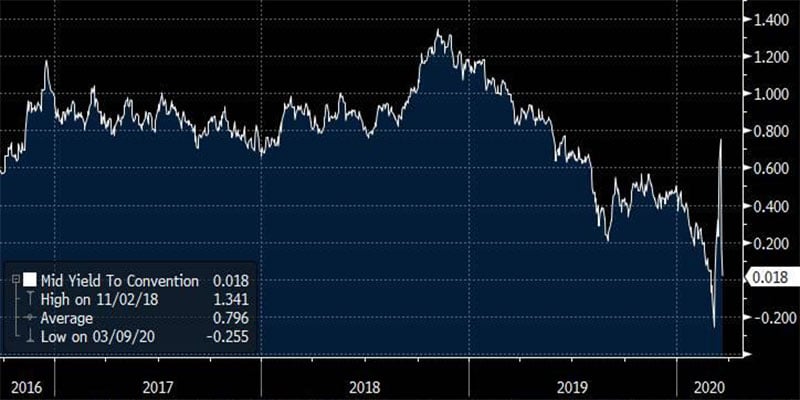
Our aim at that point was to build the allocation around the 1-1.2% and then we sold a portion of the allocation at 0.7%. Since the end of January 2020 where the allocation was 6.8% we halved the position at an average sale yield of around 0%. Post this, the US 10-year Treasury Inflation Index (TII) yields dropped to -0.51% before rising above 0.7%, then falling again.

Figure 1: Historic us 10-year tii yields
Index
Source: Bloomberg, 23/3/2020
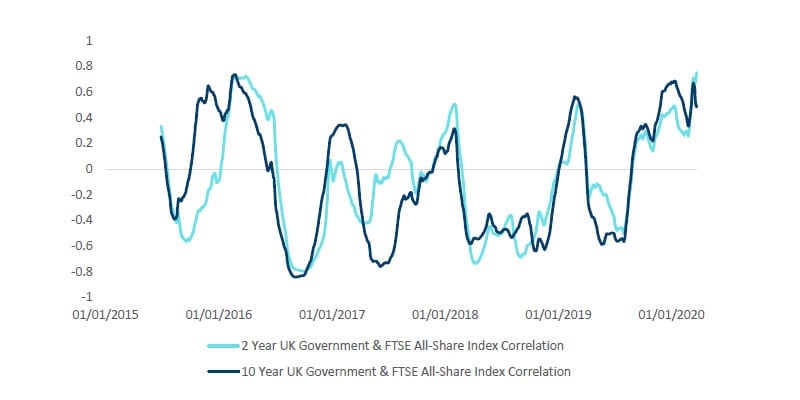
The moves we have seen in markets have been startling, but even more so the volatility we have seen in what is considered to be risk-free US government index-linked securities. This with the background of rising correlations across asset classes has meant that there are not many places to hide, so the traditional role of diversification of long-dated fixed income to equity holdings are challenged. This is a view we have held for some time, albeit we got here not through an expected route. Rather we look to use cash as the defensive position within the Fund (at the end of February we held over 20% of the Fund in cash and less than one-year UK government fixed income).

Figure 2: UK government bond/equity correlation
diagram

Source: Bloomberg, 23/3/2020

However, we still have exposure to risk assets and these have hurt performance. We have not taken any kneejerk reactions to market movements; rather, we have stuck to our multi-asset process that has been in place since the inception of the firm and has witnessed many crises before. This has meant that over the past couple of weeks when risk premia have been increasing, we have been stepping in to buy some of our favoured equity regions at what we see as attractive valuations, albeit the overall equity allocation within the fund has fallen.
We do not know when the bottom of the market will be and so we have been patient with these increases taking our time, engaging with our wider equity, fixed income, commodity and property colleagues ensuring that as ever the whole collective thought and views of the firm is driving what we are doing.
To end as we started, we will continue to engage with you as clients as our views change and from a personal perspective all stay safe.
20 March 2020
CRAIG NOWRIE
Craig Nowrie
Client Portfolio Manager, Multi-Asset Solutions
Share article
Key topics
Related topics
Listen on Stitcher badge
Share article
Key topics
Related topics

Important Information

The research and analysis included on this website has been produced by Columbia Threadneedle Investments for its own investment management activities, may have been acted upon prior to publication and is made available here incidentally. Any opinions expressed are made as at the date of publication but are subject to change without notice and should not be seen as investment advice. Information obtained from external sources is believed to be reliable but its accuracy or completeness cannot be guaranteed.

Related Insights

14 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: Why does the Fed have to hike rates?

Central bank policy is back at the forefront of investor attention as inflation data challenges expectations of an imminent easing cycle.
8 September 2026

Senior Economist, Multi-Asset Solutions team

Delegate OCIO & Strategist

Multi-Asset Investment Outlook 2027: Technological tailwind, geopolitical headwind

The global economy has proved more resilient than many expected, but the investment landscape of 2027 looks materially different from a year ago – shaped by conflict in the Middle East, a reversal in interest rate expectations, and an AI-driven capital expenditure (capex) boom of unprecedented scale.
7 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: Second guessing the central banks

Central banks are back in focus as investors enter a busy run of September policy meetings. The European Central Bank meets this week, followed by the Bank of England, the US Federal Reserve and the Bank of Japan next week.
17 September 2026

Senior Portfolio Manager, Investment Grade Credit

Hyperscaler debt issuance: A technical opportunity in investment grade credit

AI hyperscalers are reshaping the IG credit market, creating attractive dislocations in fundamentally strong issuers – and an attractive entry point.
16 September 2026

Euro LDI Update: Political risks complicate the trajectory for fiscal reform

Europe’s LDI landscape is being shaped by weaker growth, persistent inflation pressures and rising debt issuance, with political uncertainty in France and Italy adding further pressure to long-term yields.
15 September 2026

In Credit Weekly Snapshot – No more zeros

With average interest rates of 14.7% over the past four millennia, and 4.7% over the past 400 years, the real anomaly was the zero-rate period of the 2000s.
true
true

Important Information

The research and analysis included on this website has been produced by Columbia Threadneedle Investments for its own investment management activities, may have been acted upon prior to publication and is made available here incidentally. Any opinions expressed are made as at the date of publication but are subject to change without notice and should not be seen as investment advice. Information obtained from external sources is believed to be reliable but its accuracy or completeness cannot be guaranteed.

You may also like

Investment approach

Teamwork defines us and is fundamental to our investment approach, which is structured to facilitate the generation, assessment and implementation of good, strong investment ideas for our portfolios.

Funds and Prices

Columbia Threadneedle Investments has a comprehensive range of investment funds catering for a broad range of objectives.

Investment Strategies

We offer a broad range of actively managed investment strategies and solutions covering global, regional and domestic markets and asset classes.
Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.