at
AT
Austria
de-AT
at_inst_classes
inst
Institutional
de
de
For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients).
Animated graphic of a stock market performance chart mimicking a wave

Insights

AI bond supply: Why the market can absorb the coming wave

Paul Smillie
Paul Smillie
Senior Credit Analyst

Strong demand, robust issuer fundamentals and clearer communication should help the market absorb the expected surge in artificial intelligence-related bond issuance.

There’s a moment in the Wizard of Oz where the terrifying wizard turns out to be a nervous man pulling levers behind a curtain. Once revealed the wizard seems a lot less imposing. We think the same trick applies to one of the credit markets‘ current favourite scare stories: the coming wave of investment grade (IG) bond supply driven by spending on artificial intelligence (AI).1

Granted, the headline numbers do look frightening. Hyperscalers are set to spend around $6 trillion on AI infrastructure over the next five years. Some of that will be funded with debt, and some of that debt will land in IG bond markets. Adding it up you get forecasts of elevated net supply for years to come. Cue nervous conversations about spread widening, market indigestion and the return of the „bond vigilantes“.

We have taken a good long look at this and believe that, once you pull back the curtain, the numbers are far less alarming than the popular narrative suggests.

Debt just needs to keep pace with earnings

Over time, corporate debt tends to grow broadly in line with earnings, as management teams, rating agencies and bondholders constrain leverage. If earnings double, debt can roughly double while the ratio between them remains stable. This is the normal pattern of a growing economy.

For the IG bond index, we expect earnings (EBITDA) to grow by more than 10% annually over the next couple of years. If leverage remains flat, that implies roughly $1 trillion of net new supply each year to the US market. Including refinancing, gross issuance could reach $1.75 trillion-$2 trillion annually. These are large numbers, but they largely reflect bigger company balance sheets and a growing economy.

Figure 1 shows our forecasts for EBITDA growth and leverage for the dollar IG universe. Despite forecasting a modest deleveraging, we still expect more than $1.8 trillion of net new supply between FY25 and FY27.

Figure 1: Dollar IG EBITDA and debt growth ($ billions, LHS) and leverage (RHS)
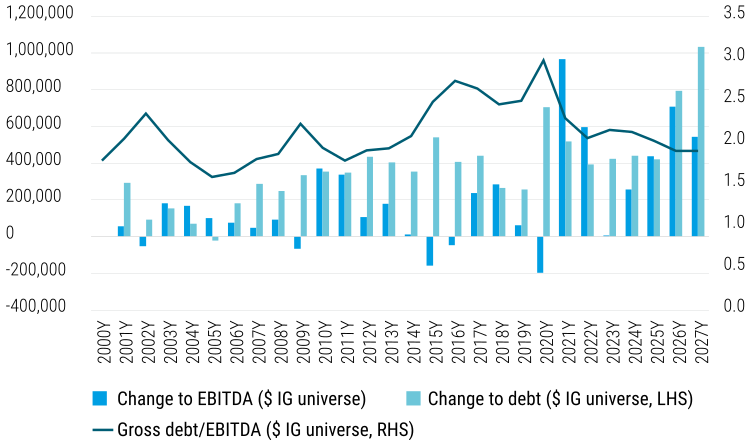
Figure 1: Dollar IG EBITDA and debt growth ($ billions, LHS) and leverage (RHS)

Source: Columbia Threadneedle Investments’ analysis of Bloomberg data, October 2026

The AI bit is smaller than it looks

Against this backdrop, we estimate that hyperscalers will fund around $4.5 trillion of AI spending from free cash flow and $1.5 trillion through debt. Only about $1 trillion is likely to pass through IG markets. Spread over five years, that is roughly $200 billion of additional annual tech supply annually, albeit with some front-loading. This is a meaningful amount, but manageable for a market that already absorbs trillions of dollars of issuance each year.

More important than the overall volume is its concentration. The supply will come from a small group of very large technology companies, increasing their weight in corporate bond indices much as the “Magnificent Seven” have come to dominate equity indices. That shift warrants attention, but concentration is not inherently dangerous if the underlying businesses remain strong and issuers communicate clearly.

There is also useful historical context. Over the past decade, technology earnings grew much faster than debt, reducing sector leverage from 1.8 times earnings to 0.8 times (Figure 2). Had borrowing kept pace with earnings, these companies might have issued something like an additional $1.1trillion of bonds. AI-related borrowing therefore looks less like a new imbalance than a partial return towards a more normal relationship between earnings and debt.

Figure 2: Technology sector debt ($ billions, LHS) and leverage (RHS)
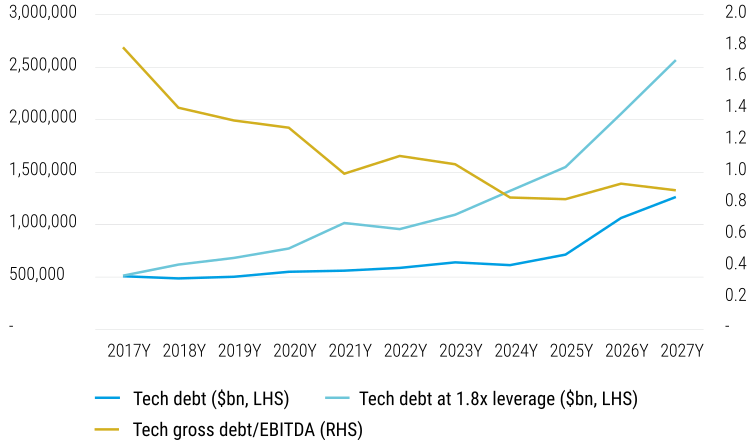
Figure 2: Technology sector debt ($ billions, LHS) and leverage (RHS)

Source: Bloomberg, as of October 2026

History offers a useful playbook

Previous supply surges offer a useful comparison. After the global financial crisis (GFC), banks issued debt to meet regulatory requirements; telecom companies borrowed to fund network investment; and energy companies funded the shale boom. Each sector increased its share of the bond index by a similar amount, but market outcomes differed. Bank issuance, as required by the regulators, was accompanied by clear, well-signalled disclosures and caused little spread disruption. In telecoms and energy, faster leverage growth and less clarity contributed to sharper widening.

The lesson is that uncertainty matters more than supply alone. Investors are generally more receptive when companies explain how much they plan to borrow, why they need the capital and how they will manage leverage. If technology issuers follow the banks’ example, the market should absorb the additional bonds with less disruption than current fears imply.

Encouragingly, technology companies are becoming more disciplined in their communication with bond investors, including setting explicit guardrails for issuance. Greater clarity makes us more comfortable with the risk and more inclined to view any associated spread widening as a potential opportunity rather than a warning.

Who is buying all these bonds?

The debate also tends to overlook demand, which remains strong. Exporting economies in Asia continue to recycle savings into US bonds. Better-funded pension schemes are natural buyers of long-dated corporate debt, while insurers need high-quality bonds to match growing liabilities. Household inflows into IG bond funds provide further support. In aggregate, demand appears capable of absorbing the expected supply.

So, is the ‘wizard’ actually dangerous?

Not obviously so. AI-driven issuance is real, but it looks less threatening once placed in the context of normal balance-sheet growth and strong demand. The greater risk is not the volume of bonds itself, but whether issuers are transparent about their plans. With clear communication and disciplined leverage, the outcome could resemble post-GFC bank issuance: a substantial, well-signalled increase that the market absorbs without major disruption.

The wizard’s power depended on perception. We suspect concerns about IG supply may also prove overstated once the numbers are examined more closely. The scale is substantial, but the market has absorbed comparable shifts before; this one should be judged on issuer fundamentals, leverage and transparency rather than headline figures alone.
Hauptthemen

Abonnieren Sie Insights

Optimieren Sie unsere auf Sie zugeschnittene E-Mail, indem Sie die Arten von Insights und Informationen, die Sie von uns erhalten möchten, individuell anpassen.

Aktuelle Beiträge

Strong demand, robust issuer fundamentals and clearer communication should help the market absorb the expected surge in artificial intelligence-related bond issuance.
Discover how system-level stewardship helps investors address systemic risks through engagement with policymakers, regulators and market standards.
Higher-for-longer rate expectations and geopolitical tensions shaped UK LDI funding markets in Q3, while resilient repo liquidity, rising year-end costs and broader funding options kept flexibility firmly in focus.
Hauptthemen
Verwandte Themen

1 Columbia Threadneedle Investments, Hyperscaler debt issuance: A technical opportunity in investment grade credit, 17 September 2026

Important information

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients). For marketing purposes.

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk.  Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414.  TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act 2001 (Cth) and relies on Class Order 03/1102 in respect of the financial services it provides to wholesale clients in Australia. This document should only be distributed in Australia to “wholesale clients” as defined in Section 761G of the Corporations Act.  TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Investment Management Association of Japan and Type II Financial Instruments Firms Association.

In the UK: Issued by Threadneedle Asset Management Limited, No. 573204 and/or Columbia Threadneedle Management Limited, No. 517895, both registered in England and Wales and authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A., registered with the Registre de Commerce et des Sociétés (Luxembourg), No. B 110242 and/or Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

In the Middle East: This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA).  For Distributors: This document is intended to provide distributors with information about Group products and services and is not for further distribution. For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

This document may be made available to you by an affiliated company which is part of the Columbia Threadneedle Investments group of companies: Columbia Threadneedle Management Limited in the UK; Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. © 2026 Columbia Threadneedle. All rights reserved.

Verwandte Beiträge

13 Oktober 2026

In Credit Weekly Snapshot – The real thing

Inflation continues to influence government finances, with UK real yields nearing 2%, their highest level since 2008, and US real yields approaching 3%.
6 Oktober 2026

In Credit Weekly Snapshot – Move it

Bond markets are moving to a beat that equity markets have yet to hear. The MOVE Index has surged while the VIX remains near its lows – a divergence that has historically preceded broader risk repricing.
5 Oktober 2026

Artificial intelligence: implications for the economy and equity and fixed income markets

Artificial intelligence has moved from a narrow technology theme to a broad investment, productivity and financing cycle that will impact almost every aspect of financial markets.
20 Oktober 2026

Global Head of Research

Global Head, Responsible Investment

Our approach to system-level stewardship

Discover how system-level stewardship helps investors address systemic risks through engagement with policymakers, regulators and market standards.
16 Oktober 2026

Global Head of LDI

Q3 2026 repo update

Higher-for-longer rate expectations and geopolitical tensions shaped UK LDI funding markets in Q3, while resilient repo liquidity, rising year-end costs and broader funding options kept flexibility firmly in focus.
15 Oktober 2026

Asset Allocation update - Q4 2026

Economies and financial markets remain resilient despite heightened inflation risks. These are shaping central bank policy and interest-rate expectations, pushing bond yields to levels not seen since before the global financial crisis.

Important information

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients). For marketing purposes.

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk.  Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414.  TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act 2001 (Cth) and relies on Class Order 03/1102 in respect of the financial services it provides to wholesale clients in Australia. This document should only be distributed in Australia to “wholesale clients” as defined in Section 761G of the Corporations Act.  TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Investment Management Association of Japan and Type II Financial Instruments Firms Association.

In the UK: Issued by Threadneedle Asset Management Limited, No. 573204 and/or Columbia Threadneedle Management Limited, No. 517895, both registered in England and Wales and authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A., registered with the Registre de Commerce et des Sociétés (Luxembourg), No. B 110242 and/or Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

In the Middle East: This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA).  For Distributors: This document is intended to provide distributors with information about Group products and services and is not for further distribution. For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

This document may be made available to you by an affiliated company which is part of the Columbia Threadneedle Investments group of companies: Columbia Threadneedle Management Limited in the UK; Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. © 2026 Columbia Threadneedle. All rights reserved.

Icon checked

Vielen Dank. Sie können jetzt Ihr Präferenzzentrum besuchen, um auszuwählen, welche Insights Sie per E-Mail erhalten möchten.

Icon checked

Vielen Dank. Sie können jetzt Ihr Präferenzzentrum besuchen, um auszuwählen, welche Insights Sie per E-Mail erhalten möchten.

Icon checked

Vielen Dank. Sie können jetzt Ihr Präferenzzentrum besuchen, um auszuwählen, welche Insights Sie per E-Mail erhalten möchten.

Bitte bestätigen Sie einige Angaben zu Ihrer Person, um Ihr Präferenzzentrum zu besuchen

*Pflichtfelder

Etwas ist schiefgelaufen, bitte versuchen Sie es erneut

Vielen Dank. Sie können jetzt Ihr Präferenzzentrum besuchen, um auszuwählen, welche Einblicke Sie per E-Mail erhalten möchten.

Um zu sehen und zu aktualisieren, welche Erkenntnisse Sie von uns per E-Mail erhalten, besuchen Sie bitte Ihr Preference Center.