lu
LU
Luxembourg
en-LU
lu_inst_classes
inst
Institutional
en
en
For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients).
Abstract AI and data analytics visualization with blue and orange digital graphics.

Insights

Hyperscaler debt issuance: A technical opportunity in investment grade credit

Andrew Dewar
Andrew Dewar
Senior Portfolio Manager, Investment Grade Credit

AI hyperscalers are reshaping the IG credit market, creating attractive dislocations in fundamentally strong issuers – and an attractive entry point.

The artificial intelligence (AI) buildout is reshaping the investment grade (IG) corporate bond market in real time. Technology companies racing to build AI infrastructure – dubbed “hyperscalers” for the unprecedented pace of their capital spending – are flooding the market with new debt. This wave of issuance is creating something we don’t often see: fundamentally strong credits trading at technically driven wide spreads.

The scale of investment is staggering, with the competitive dynamics of the AI race compelling them to bring forward capital expenditure (capex) plans. Issuance has accelerated from just $20 billion in 2024 to $136 billion in 2025, with $256 billion issued year-to-date in 2026.1 Hyperscaler capex estimates for 2027 alone have surged to $968 billion, up from the $600 billion that was projected late last year.2 While these companies generate substantial internal cash flows, roughly 20%-25% of their funding requirements are being financed through IG markets.

This surge is materially reshaping the IG universe. Technology sector exposure in the Global Corporate Aggregate index has increased to 8.4% from 6.7% in May 2024. Measured by contribution to duration (CTD) – a gauge of how much each sector drives the index’s sensitivity to spread moves – technology now represents 0.5 years of the index’s 5.6-year spread duration, up from 0.4 years a year ago. In other words, the sector is becoming a larger source of benchmark risk, not merely a larger slice of issuance.

More tellingly, when we look at duration times spread, our preferred measure of risk-weighted benchmark allocation, the impact is stark. Oracle now ranks as the largest risk contributor to global corporate indices, jumping from 10th place just a year ago. Meta, Google, and Amazon have similarly vaulted into the top 20, climbing more than 100 positions each.

The technical pressure

To absorb this volume of issuance, markets are demanding a concession. As such, the technology sector is now trading approximately two standard deviations cheap versus the US corporate index, despite credit fundamentals remaining robust (Figure 1). These are AA-rated companies with low leverage, strong earnings growth and solid cash flow generation. The capex spending is adding only modest leverage – perhaps 0.1x-0.2x – to balance sheets that started from very strong positions.

Figure 1: Issuance pressure has pushed tech spreads wider

ICE BofA ML Tech option-adjusted spread / ICE BofA US Corp Index OAS
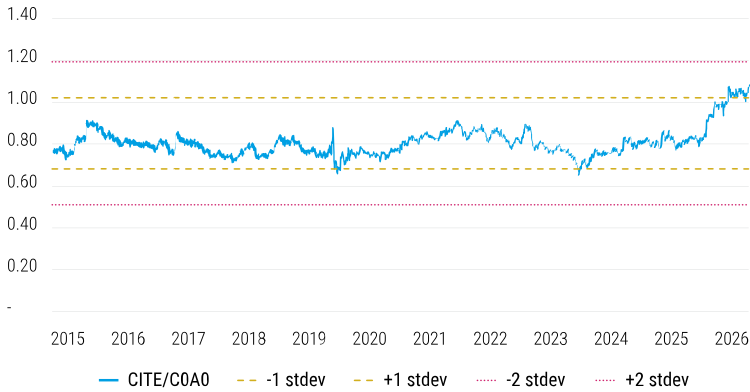
Line chart showing technology credit spreads versus the US corporate bond index. Tech spreads remain relatively stable until 2024, then rise sharply in 2025-2026, reaching near +2 standard deviations as increased bond issuance widens spreads.

Source: Bloomberg, September 2026

The issuers recognise the digestion challenge and are responding strategically by diversifying funding sources. We are seeing increased issuance in non-US dollar currencies in order to tap fresh investor bases (Figure 2).

Figure 1: Issuance pressure has pushed tech spreads wider

Total hyperscaler issuance by currency ($bn)
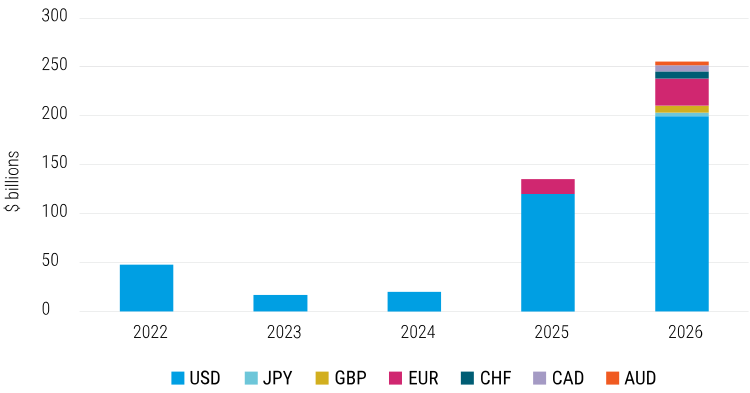
Stacked bar chart of currency allocations from 2022 to 2026, dominated by USD and growing substantially by 2026.

Source: Bloomberg/Columbia Threadneedle analysis, September 2026

More notably, hyperscalers are turning to different investment structures such as Special Purpose Vehicles (SPVs), with $70 billion now issued through benchmark-eligible SPVs like the pioneering $27 billion Meta/Beignet transaction. These highly structured, asset-backed vehicles spread funding risk beyond traditional unsecured corporate bond investors. Private markets may also act as a release valve, providing alternative funding channels if public market spreads show further signs of indigestion.

An attractive entry point

From our bottom-up, fundamental credit research perspective, this presents a compelling opportunity. In this instance, the spread widening is driven by market technicals (investor capacity constraints and supply concerns) rather than material deteriorating credit quality. Revenue growth from AI investments is validating the capex decisions, and once this investment cycle moderates, we expect free cash flow generation to strengthen materially.

That said, we remain vigilant. Our downside risk management framework includes monitoring revenue forecasts that justify the expenditure and maintaining appropriate issuer concentration limits. We are also cautious about overly complex SPV structures that may obscure underlying risks.

The current environment exemplifies why fundamental research matters: it allows us to distinguish between technical dislocations and genuine credit deterioration, positioning portfolios to exploit the former while avoiding the latter.
Key topics

Subscribe to insights

Get the most out of your email by tailoring the types of insights and information you would like to receive from us.

Latest articles

AI hyperscalers are reshaping the IG credit market, creating attractive dislocations in fundamentally strong issuers – and an attractive entry point.
Europe’s LDI landscape is being shaped by weaker growth, persistent inflation pressures and rising debt issuance, with political uncertainty in France and Italy adding further pressure to long-term yields.
With average interest rates of 14.7% over the past four millennia, and 4.7% over the past 400 years, the real anomaly was the zero-rate period of the 2000s.
Key topics
Related topics

1 Bloomberg, 4 September 2026
2 Bloomberg/Columbia Threadneedle analysis, September 2026. Hyperscalers defined as Amazon, Alphabet, Meta, Microsoft and Oracle.

Important information

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients). For marketing purposes.

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk. Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414. TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act 2001 (Cth) and relies on Class Order 03/1102 in respect of the financial services it provides to wholesale clients in Australia. This document should only be distributed in Australia to “wholesale clients” as defined in Section 761G of the Corporations Act. TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Investment Management Association of Japan and Type II Financial Instruments Firms Association.

In the UK: Issued by Threadneedle Asset Management Limited, No. 573204 and/or Columbia Threadneedle Management Limited, No. 517895, both registered in England and Wales and authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A., registered with the Registre de Commerce et des Sociétés (Luxembourg), No. B 110242 and/or Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

In the Middle East: This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA). For Distributors: This document is intended to provide distributors with information about Group products and services and is not for further distribution. For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

This document may be made available to you by an affiliated company which is part of the Columbia Threadneedle Investments group of companies: Columbia Threadneedle Management Limited in the UK; Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. © 2026 Columbia Threadneedle. All rights reserved.

Related Insights

15 September 2026

In Credit Weekly Snapshot – No more zeros

With average interest rates of 14.7% over the past four millennia, and 4.7% over the past 400 years, the real anomaly was the zero-rate period of the 2000s.
8 September 2026

In Credit Weekly Snapshot – China in your hand

China's bond market appears remarkably strong, but the real story lies under the surface.
25 August 2026

In Credit Weekly Snapshot – Take it to the limit (one more time)

US debt has reached $40 trillion, up by about a third in less than five years. The Treasury has tried to contain long-end pressure, but investors remain sceptical.
16 September 2026

Euro LDI Update: Political risks complicate the trajectory for fiscal reform

Europe’s LDI landscape is being shaped by weaker growth, persistent inflation pressures and rising debt issuance, with political uncertainty in France and Italy adding further pressure to long-term yields.
15 September 2026

In Credit Weekly Snapshot – No more zeros

With average interest rates of 14.7% over the past four millennia, and 4.7% over the past 400 years, the real anomaly was the zero-rate period of the 2000s.
14 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: Why does the Fed have to hike rates?

Central bank policy is back at the forefront of investor attention as inflation data challenges expectations of an imminent easing cycle.

Important information

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients). For marketing purposes.

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk. Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414. TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act 2001 (Cth) and relies on Class Order 03/1102 in respect of the financial services it provides to wholesale clients in Australia. This document should only be distributed in Australia to “wholesale clients” as defined in Section 761G of the Corporations Act. TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Investment Management Association of Japan and Type II Financial Instruments Firms Association.

In the UK: Issued by Threadneedle Asset Management Limited, No. 573204 and/or Columbia Threadneedle Management Limited, No. 517895, both registered in England and Wales and authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A., registered with the Registre de Commerce et des Sociétés (Luxembourg), No. B 110242 and/or Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

In the Middle East: This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA). For Distributors: This document is intended to provide distributors with information about Group products and services and is not for further distribution. For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

This document may be made available to you by an affiliated company which is part of the Columbia Threadneedle Investments group of companies: Columbia Threadneedle Management Limited in the UK; Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. © 2026 Columbia Threadneedle. All rights reserved.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.