GB
gb
GB
en-GB
gb_inst_classes
inst
Institutional
en
en
Insights

Seeking out good alpha opportunities in emerging market debt

  • The steady recovery of the asset class since Q2 has been every bit as remarkable as the initial blow-out in spreads back in March. Much of the higher-rated EM universe now trades at spreads over US Treasuries roughly equivalent to those prevailing at the start of the year.
  • With valuations in EM sovereigns around long-run averages – and with balance sheet risks now more pronounced – we are cautious about the potential for significant further spread tightening in hard-currency fixed income. But total return opportunities in the year ahead remain attractive, especially when accompanied by judicious credit selection.
  • A steady global growth recovery supported by more constructive and multilateral US trade policy may just create ideal conditions for EM currencies to correct some of their underperformance against the US dollar.
  • The semi-mature state of EMD markets creates good alpha opportunities across sovereigns and corporates in both hard and local currencies.

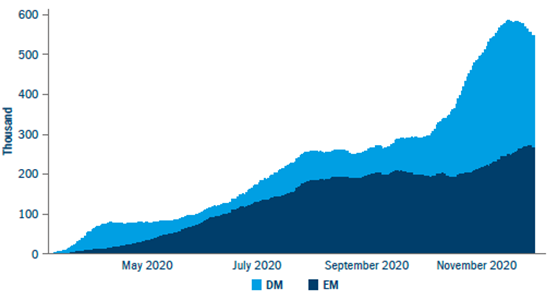
The legacy of Covid-19 in emerging markets (EMs) may take some time to become clear. Having lagged advanced economies’ initial surge in cases in March and April, lower income countries experienced highly concerning case growth at the end of the summer, before once again being eclipsed by the developed markets’ second wave (Figure 1).

There are reasons to expect a slower and less comprehensive vaccine roll-out among EMs than in richer countries, and the fiscal damage done to already-fragile sovereign balance sheets may increase vulnerabilities.
But the steady recovery of the asset class since Q2 has been every bit as remarkable as the initial blow-out in spreads back in March. Much of the higher-rated EM universe now trades at spreads over US Treasuries roughly equivalent to those prevailing at the start of the year.
With valuations in EM sovereigns around long-run averages – and with balance sheet risks now more pronounced – we are cautious about the potential for significant further spread tightening in hard-currency fixed income. But total return opportunities in the year ahead remain attractive, especially when accompanied by judicious credit selection. So far this year EMD performance has still to fully catch up with other parts of the fixed income asset class.

The structural tightening of spreads in the early years of the 21st century have given way to a much more cyclical market; the EM credit asset class displays a strong correlation with developed market corporate credit and is well positioned for even a modest global growth recovery in 2021. Moreover, the global rate environment remains conducive to EMD performance with inflation benign, central banks expected to maintain accommodation and the stock of negative-yielding assets at around $15 trillion.1 Meanwhile, allocations to the asset class among international investors are still low, suggesting persistent inflows in coming years.

Figure 1: New Covid-19 cases, 7-day moving average
Seeking out good alpha opportunities Fig1
Source: WHO, November 2020.
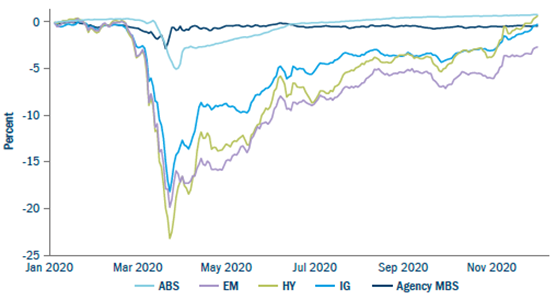
Our attention is focused on the higher-yielding end of the EM sovereign and credit markets, where performance has lagged that of both higherquality EM credits and equivalently rated developed market corporate bonds (Figure 2). The excess yield available in EMD relative to US High Yield does not adequately reflect the lower default rates and higher recovery values observed in the former.
In the EM corporate space, despite a tough year for revenues and increased gross leverage, balance sheets tend to be rich with undeployed cash and deleveraging potential as earnings recover next year. As ever, selectivity and discerning fundamental analysis are essential.
EM local currency bonds also present an interesting opportunity as we move into the next phase of the Covid cycle. The combination of deteriorating fiscal health, as governments rushed to insulate their economies, and aggressive monetary easing enabled by tame inflation, has left many local currency yield curves unusually steep.
It will be unwise to ignore the vulnerabilities implied by those policies over the longer run. But relative to those on offer in advanced economies, real yields are attractive even on a currency-hedged basis.
More importantly for returns, a steady global growth recovery supported by more constructive and multilateral US trade policy may just create ideal conditions for EM currencies to correct some of their underperformance against the US dollar.
As ever, the semi-mature state of EMD markets creates good alpha opportunities across sovereigns and corporates in both hard and local currencies. We continue to focus on pairing rigorous, fundamental analysis with macro research to identify the best risk/reward opportunities.

Figure 2: YTD excess returns by sector
Seeking out good alpha opportunities Fig2
Source: Bloomberg, November 2020.
21 December 2020
Share article
Key topics
Related topics
Listen on Stitcher badge
Share article
Key topics
Related topics

1 Bloomberg, Negative-Yielding Debt Hits Record $15 Trillion on Trade Woes, 5 August 2019.

Important Information

The research and analysis included on this website has been produced by Columbia Threadneedle Investments for its own investment management activities, may have been acted upon prior to publication and is made available here incidentally. Any opinions expressed are made as at the date of publication but are subject to change without notice and should not be seen as investment advice. Information obtained from external sources is believed to be reliable but its accuracy or completeness cannot be guaranteed.

Related Insights

11 November 2026

Senior Client Portfolio Manager, Fixed Income

Navigating the rate repricing: European short-term high yield

With inflation sticky, interest rates rising and volatility elevated, investors could consider short-term European high yield in order to stay invested while reducing exposure to duration risk.
10 November 2026

In Credit Weekly Snapshot – Roller coaster

Oil prices have had a wild ride so far this year, and bonds have tracked every move. A lasting settlement in the Middle East could see yields move lower.
3 November 2026

In Credit Weekly Snapshot – Tech it to the limit

The AI financing wave is weighing on the weakest credits within high yield. The key question is, will the stress be contained at the bottom of the spectrum?
11 November 2026

Senior Client Portfolio Manager, Fixed Income

Navigating the rate repricing: European short-term high yield

With inflation sticky, interest rates rising and volatility elevated, investors could consider short-term European high yield in order to stay invested while reducing exposure to duration risk.
10 November 2026

In Credit Weekly Snapshot – Roller coaster

Oil prices have had a wild ride so far this year, and bonds have tracked every move. A lasting settlement in the Middle East could see yields move lower.
9 November 2026

Senior Economist, EMEA

Market Perspectives: Making sense of the midterms

The US midterm elections have delivered a clear outcome: the Democrats will take control of both the House and the Senate from January 2027.
true
true

Important Information

The research and analysis included on this website has been produced by Columbia Threadneedle Investments for its own investment management activities, may have been acted upon prior to publication and is made available here incidentally. Any opinions expressed are made as at the date of publication but are subject to change without notice and should not be seen as investment advice. Information obtained from external sources is believed to be reliable but its accuracy or completeness cannot be guaranteed.

You may also like

Investment approach

Teamwork defines us and is fundamental to our investment approach, which is structured to facilitate the generation, assessment and implementation of good, strong investment ideas for our portfolios.

Funds and Prices

Columbia Threadneedle Investments has a comprehensive range of investment funds catering for a broad range of objectives.

Investment Strategies

We offer a broad range of actively managed investment strategies and solutions covering global, regional and domestic markets and asset classes.

Recent Microsoft outages


Due to the recent global Microsoft outages, if you have a question or query that needs urgent attention please get in touch with your usual Columbia Threadneedle representative via telephone.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.