dk
DK
Denmark
en-DK
dk_inst_classes
inst
Institutional
en
en
For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients).
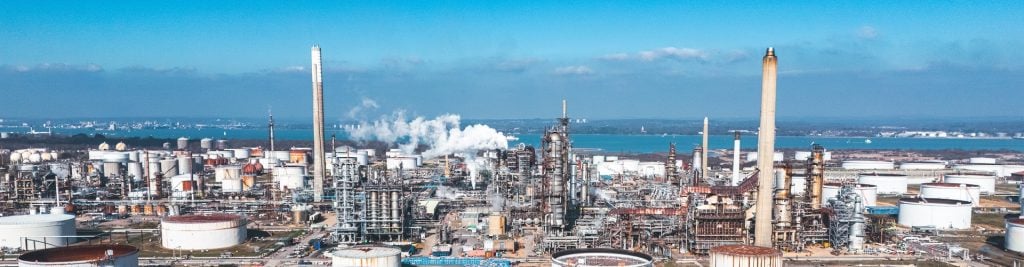
Panoramic view of a large industrial refinery with storage tanks, processing equipment, tall chimneys, and steam emissions, set against a blue sky and waterfront.

Insights

Market Perspectives: Why is oil stuck at $100/barrel?

Anthony Willis
Senior Economist, Multi-Asset Solutions team

Key Takeaways

  • Oil exports through the Strait of Hormuz have recovered to an estimated 85–90% of pre-conflict volumes, but prices remain elevated.
  • Supply-chain disruption, inventory rebuilding and renewed attacks on shipping continue to prevent a decisive normalisation in the oil market.
  • Uncertainty surrounding Iran and the Russia–Ukraine war leaves energy supplies exposed to further interruptions and geopolitical risk.
  • Constrained global refining capacity is keeping diesel and other refined-product prices high even as crude flows improve.
  • For investors, stronger physical supply is encouraging, but persistent bottlenecks and security risks are likely to sustain volatility and a substantial risk premium.

Oil markets have received some comparatively encouraging signals from the Middle East, but the improvement in physical supply has yet to translate into a decisive fall in prices. Shipping traffic through the Strait of Hormuz increased during September, with both visible and less readily tracked transits moving higher. Flows have recovered to an estimated 85–90% of pre-conflict volumes, helping to contain further upward pressure on crude prices.

However, restoring crude flows is only part of the challenge. Supply chains remain disrupted, while the rebuilding of inventories is sustaining demand. As a result, the recovery in exports has not produced a commensurate decline in oil prices. Renewed attacks on shipping in October, together with the first US retaliation over the weekend, also underline that the route back to normality is unlikely to be smooth.

The underlying dispute remains unresolved. Iran is seeking to impose its own terms on traffic through the Strait of Hormuz, while the US is pushing back. Although the increase in shipping volumes offers a plausible pathway towards more normal conditions, the recent escalation demonstrates that the risk of interruption remains material. The possibility of further US military action also means that investors cannot discount a renewed broadening of the conflict.

Developments in the Russia–Ukraine war add a second source of uncertainty. Reports of a potential ceasefire covering energy infrastructure would, if implemented, be constructive. Russia’s refining network has sustained significant damage from Ukrainian attacks, constraining the supply of refined products. Yet the latest reports appear to have surprised Ukraine, have not been confirmed by Russia and follow similar headlines in September that ultimately led nowhere. For markets, this argues for caution rather than an assumption of imminent relief.

The distinction between crude oil and refined products is particularly important. Pressure on refining capacity leaves diesel prices substantially higher relative to crude. US refineries are operating close to their limits, European capacity is constrained, Russian utilisation has fallen sharply and Middle Eastern refining remains disrupted by the conflict. Even if crude supply improves, bottlenecks in the refining system could keep diesel and other product prices elevated.

For the US administration, that creates an immediate political and economic challenge ahead of the midterm elections. Measures intended to ease the burden on consumers may provide some support, but they are unlikely to lower diesel prices materially in the near term. More broadly, the pressure is not confined to transport fuels. Continued disruption also affects liquefied natural gas, sulphur, fertiliser and other products that depend on secure regional trade routes.

Politically, the situation still resembles a stalemate. Negotiations may create scope for de-escalation, but Iran appears prepared to absorb economic pressure and pursue a longer-term strategy. The regime remains in place and has shown little willingness to concede on the negotiating positions discussed earlier in the year. That limits the prospect of a rapid diplomatic resolution and leaves energy markets exposed to further bouts of volatility.

The central message is that better shipping data should not be mistaken for a complete solution. Higher transit volumes through the Strait of Hormuz are a positive development, but fragile security, limited refining capacity and persistent geopolitical risk are likely to keep oil and refined-product prices elevated. At the same time, the global economy’s resilience and ability to adapt over the past two months have been encouraging. Markets may therefore continue to balance improving physical supply against a still-substantial risk premium.
Key topics

Subscribe to insights

Get the most out of your email by tailoring the types of insights and information you would like to receive from us.

Latest articles

Oil markets have received some comparatively encouraging signals from the Middle East, but the improvement in physical supply has yet to translate into a decisive fall in prices.
Artificial intelligence (AI) is driving one of the largest infrastructure investment cycles in decades. But converting billions of dollars of planned spending into operating data centres will depend on more than access to electricity.
Bond markets are moving to a beat that equity markets have yet to hear. The MOVE Index has surged while the VIX remains near its lows – a divergence that has historically preceded broader risk repricing.
Key topics
Related topics

Important information

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients).

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk. Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414. TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act and relies on Class Order 03/1102 in marketing and providing financial services to Australian wholesale clients as defined in Section 761G of the Corporations Act 2001. TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Japan Investment Advisers Association and Type II Financial Instruments Firms Association.

In UK: Issued by Threadneedle Asset Management Limited. Registered in England and Wales, Registered No. 573204, Cannon Place, 78 Cannon Street, London EC4N 6AG, United Kingdom. Authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A. Registered with the Registre de Commerce et des Societes (Luxembourg), Registered No. B 110242, 44, rue de la Vallée, L-2661 Luxembourg, Grand Duchy of Luxembourg.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA). For Distributors: This document is intended to provide distributors’ with information about Group products and services and is not for further distribution.

For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies.

Related Insights

5 October 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: Déjà vu – another bond sequel

Government bond yields are rising again – but this is not simply a repeat of 2022. We consider what fiscal pressures, inflation uncertainty and higher borrowing costs could mean for bonds, equities and portfolio positioning.
28 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: What’s in store for Q4?

Four factors are likely to have an important bearing on financial markets in the fourth quarter of 2026: US politics, fiscal policy in the UK and France, developments involving Iran, and the corporate earnings outlook.
21 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: The roadmap for central banks

After a series of policy meetings across the major central banks, the direction of travel for interest rates remains finely balanced.
7 October 2026

US Fixed Income Utilities Analyst

Senior Thematic Investment Analyst

AI data centres: Powering through the constraints

Artificial intelligence (AI) is driving one of the largest infrastructure investment cycles in decades. But converting billions of dollars of planned spending into operating data centres will depend on more than access to electricity.
6 October 2026

In Credit Weekly Snapshot – Move it

Bond markets are moving to a beat that equity markets have yet to hear. The MOVE Index has surged while the VIX remains near its lows – a divergence that has historically preceded broader risk repricing.
5 October 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: Déjà vu – another bond sequel

Government bond yields are rising again – but this is not simply a repeat of 2022. We consider what fiscal pressures, inflation uncertainty and higher borrowing costs could mean for bonds, equities and portfolio positioning.

Important information

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients).

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk. Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414. TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act and relies on Class Order 03/1102 in marketing and providing financial services to Australian wholesale clients as defined in Section 761G of the Corporations Act 2001. TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Japan Investment Advisers Association and Type II Financial Instruments Firms Association.

In UK: Issued by Threadneedle Asset Management Limited. Registered in England and Wales, Registered No. 573204, Cannon Place, 78 Cannon Street, London EC4N 6AG, United Kingdom. Authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A. Registered with the Registre de Commerce et des Societes (Luxembourg), Registered No. B 110242, 44, rue de la Vallée, L-2661 Luxembourg, Grand Duchy of Luxembourg.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA). For Distributors: This document is intended to provide distributors’ with information about Group products and services and is not for further distribution.

For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.