ch
CH
Switzerland
en-CH
ch_inst_classes
inst
Institutional
en
en
For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients).
Eiffel Tower overlooking Paris at sunset with a golden city skyline.

Insights

Euro LDI Update: Political risks complicate the trajectory for fiscal reform

Rosa Fenwick
Rosa Fenwick
Global Head of LDI

Europe faces the challenge of weaker growth, persistent inflation pressures and rising debt issuance. This is further complicated by rising political uncertainty with upcoming elections in France and Italy promoting additional yield premia. Meanwhile the ECB remains committed to its monetary tightening cycle despite the deteriorating economic backdrop.

Exogeneous geopolitical factors have buffeted Europe over the course of 2026, the Iran conflict impacting energy and production inputs and the war in Ukraine ramping up domestic defence commitments.  This pressure on both sides of the supply and demand inflation equation threatened every central bank’s nightmare – that of stagflation, where the economy fails to grow but inflation runs rampant.  Whilst the global (ex-US) discomfort with President Trump could presage a cycling of demand into European fixed income, this is counterbalanced by the expansion in issuance, not helped by the hyperscalers targeting Europe as the secondary liquidity centre outside the US.  Issuance by these entities including Amazon, Alphabet, Meta, Microsoft and Oracle in the first half of 2026 has already massively exceeded that of the entire year of 2025.  This wall of supply has put further pressure on long-term yields that are already sensitive to the changes to Dutch pension regulation.  Whilst the picture is complicated by individual approaches to current and future hedging and timing choices, there is no doubt that demand for long-dated debt from Dutch schemes will decrease.  This is the challenging backdrop to increased political risks as the season of elections approaches, including France and Italy.

French political instability dominated headlines last year as the revolving door of prime ministers managed to return a previous one, adopting a more conciliatory tone to fiscal reform to balance the complex parliamentary mathematics.  This allowed other geopolitical considerations to take centre stage – yet with no end in sight to either the Ukraine or Iran conflict, eyes have returned to the situation in France.  The centrists will be hoping that this election will restore their position allowing greater ambition in reducing spending; however, on current polling that appears unlikely.  The Le Pen appeal may have succeeded in shortening the ban from public office allowing her to run in the coming elections; however, the conviction for public funds embezzlement was upheld – hardly a ringing endorsement of an ambitious public figure with sights on the presidency.  The base case scenario for many political commentators is a run-off between the far-right and the far-left.  That may be a binary choice in politics, but both parties have limited interest in curbing the growth of the state so may end up being relatively similar from a market perspective.  As a consequence, the yield that investors need to receive to hold French debt versus German debt has increased to levels last seen during the height of recent political crises, indicating markets have already priced in political and fiscal risks.  However, French yields could remain under pressure, particularly amid extended uncertainty over budget negotiations.  The chart below shows that 10-year French debt has a higher yield versus swaps than Italy.  Anecdotally it is believed that hedge fund positioning in French relative value spreads is short, implying further underperformance expected.

Relative value in Euro Governments
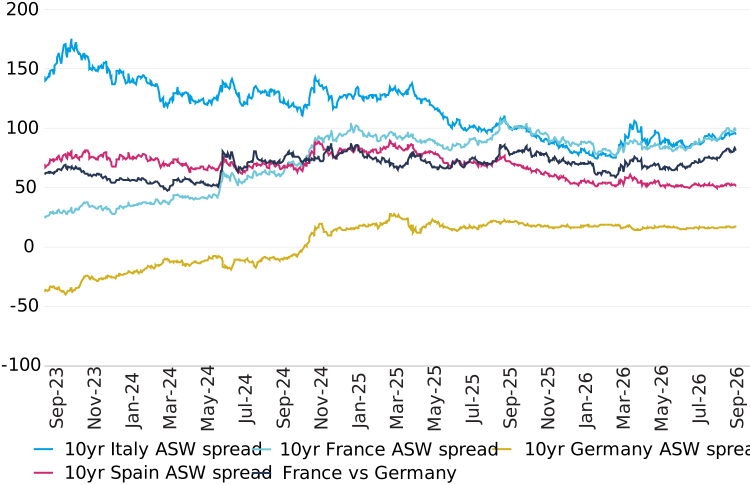
Chart comparing 10-year ASW spreads for Italy, France, Spain and Germany from 2023 to 2026.

Chart 1: Movement in relative value of key Euro governments bonds
Source: Barclays Live.  As at 4 September 2026

Italy, meanwhile, has remained somewhat under the radar but, as ever, the maths of coalitions can make outcomes hard to predict.  The recent stability under the leadership of Prime Minister Giorgia Meloni in a centre-right coalition has helped, however the polling of that grouping is suffering in recent months, impacted by the success of a new right-wing party now polling of around 7% making it the fourth largest party.  The general election is expected in April 2027, although it has not yet been announced.

Meanwhile the European Central Bank is firmly tackling the risks of inflation by committing to their hiking trajectory with the market pricing in a 99% likelihood of a rate hike at the September meeting at the time of writing and a 95% expectation of a further hike in December.  This can be set against an ‘active’ hold in the UK and rhetoric rather than action in the US despite the new Fed Chair.

Market trends

Minimum reserve requirement (MRR)

The ECB is mulling an increase in the reserve requirements that banks are required to place at the central bank to ensure sufficient capital in the event of market turmoil.  Proposals suggest that this reserve requirement could increase from 1% to 2%.  Banks typically hold excess liquidity in the deposit facility so this does not appear designed to tackle a concern around bank reserves, rather, by redefining the requirement it would reduce interest costs for the ECB.  This is because the required reserves attract a 0% interest return versus the deposit facility rate ~ expected savings are in the region of c. EUR 4bn at current rates.  This move could also make room for the ECB to continue its hiking cycle whilst mitigating the cost.  The consensus is that this would have limited but non-trivial implications for funding liquidity and short-term asset swap spreads as banks would endeavour to fill this return gap.  The key expectation is that this is unlikely to materially impact outright yields.  However, there are some more negative views, centring on the uneven distribution of excess reserves across the Eurozone’s banks and a concern that in the event of market upset this reduces liquidity just when it is needed most.  It is also possible that this could worsen month- or quarter-end volatility in ESTR and repo rates – a key focus for central banks.

LCH margin requirements

LCH has noted a reduction in cash posted as collateral for margin.  In the name of robust liquidity provisions, they therefore have enacted a 25% minimum cash collateral requirement for clearing members.  As posting cash is inefficient, most client users of clearing services will post bonds to meet initial margin requirements, resulting in clearing members having to translate bond collateral into cash to meet this; thus, putting further pressure on the funding markets.

These developments contribute to the growing trend of higher demand for liquid assets which, if considered independently, could miss a broader impact on the stability of markets.

If you would like to discuss any of the matters raised above, please contact your client representative.
Key topics

Subscribe to insights

Get the most out of your email by tailoring the types of insights and information you would like to receive from us.

Latest articles

Europe’s LDI landscape is being shaped by weaker growth, persistent inflation pressures and rising debt issuance, with political uncertainty in France and Italy adding further pressure to long-term yields.
With average interest rates of 14.7% over the past four millennia, and 4.7% over the past 400 years, the real anomaly was the zero-rate period of the 2000s.
Central bank policy is back at the forefront of investor attention as inflation data challenges expectations of an imminent easing cycle.
Key topics
Related topics

Important information:

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients). For marketing purposes.

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk.  Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414.  TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act 2001 (Cth) and relies on Class Order 03/1102 in respect of the financial services it provides to wholesale clients in Australia. This document should only be distributed in Australia to “wholesale clients” as defined in Section 761G of the Corporations Act.  TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Investment Management Association of Japan and Type II Financial Instruments Firms Association.

In the UK: Issued by Threadneedle Asset Management Limited, No. 573204 and/or Columbia Threadneedle Management Limited, No. 517895, both registered in England and Wales and authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A., registered with the Registre de Commerce et des Sociétés (Luxembourg), No. B 110242 and/or Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

In the Middle East: This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA).  For Distributors: This document is intended to provide distributors with information about Group products and services and is not for further distribution. For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

This document may be made available to you by an affiliated company which is part of the Columbia Threadneedle Investments group of companies: Columbia Threadneedle Management Limited in the UK; Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. © 2026 Columbia Threadneedle. All rights reserved.

Related Insights

1 September 2026

LDI market review and outlook August 2026 – plus ça change, plus c'est la même chose

If this sounds like a broken record that is because it is – the Strait of Hormuz has dominated global headlines since the end of February with no resolution in sight, albeit with a brief fillip for markets during the Memorandum of Understanding in mid-June until that fragile ceasefire failed to hold.
20 July 2026

Q2 2026 repo update

The Iran conflict and the impact of the closure of the Strait of Hormuz on energy prices dominated the second quarter.
29 June 2026

Euro LDI Update: Inflation pressures mark the start of a new cycle

Inflation and growth risks are back in focus, unsettling central bank easing plans and raising pressure across Eurozone markets.
15 September 2026

In Credit Weekly Snapshot – No more zeros

With average interest rates of 14.7% over the past four millennia, and 4.7% over the past 400 years, the real anomaly was the zero-rate period of the 2000s.
14 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: Why does the Fed have to hike rates?

Central bank policy is back at the forefront of investor attention as inflation data challenges expectations of an imminent easing cycle.
11 September 2026

Head of European Large Cap Equities

Europe: better momentum but structural hurdles remain

Although global growth expectations fell after the Iran conflict started, US growth expectations have crept up.

Important information:

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients). For marketing purposes.

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk.  Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414.  TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act 2001 (Cth) and relies on Class Order 03/1102 in respect of the financial services it provides to wholesale clients in Australia. This document should only be distributed in Australia to “wholesale clients” as defined in Section 761G of the Corporations Act.  TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Investment Management Association of Japan and Type II Financial Instruments Firms Association.

In the UK: Issued by Threadneedle Asset Management Limited, No. 573204 and/or Columbia Threadneedle Management Limited, No. 517895, both registered in England and Wales and authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A., registered with the Registre de Commerce et des Sociétés (Luxembourg), No. B 110242 and/or Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

In the Middle East: This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA).  For Distributors: This document is intended to provide distributors with information about Group products and services and is not for further distribution. For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

This document may be made available to you by an affiliated company which is part of the Columbia Threadneedle Investments group of companies: Columbia Threadneedle Management Limited in the UK; Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. © 2026 Columbia Threadneedle. All rights reserved.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.

Icon checked

Thank you. You can now visit your preference centre​ to choose which insights you would like to receive by email.