With inflation sticky, interest rates rising and volatility elevated, investors could consider short-term European high yield in order to stay invested while reducing exposure to duration risk.
After a prolonged period of policy accommodation, rate markets have reasserted a tightening bias on both sides of the Atlantic. For fixed income investors, the implications are material. Markets have proved resilient through much of 2026, supported by a positive economic backdrop and strong corporate earnings, but inflation and interest rate risks are building. The coming autumn could be busy and turbulent.
The tightening impulse is back – and synchronised
The US Federal Reserve (Fed) delivered a 25bp rate hike on 16 September 2026 – its first increase in more than three years – raising the benchmark Fed funds rate unanimously to a target range of 3.75%-4%. Fed funds futures now imply the overnight rate rising further to approximately 4.21% by the December Federal Open Market Committee (FOMC) meeting, with approximately 1.3 additional hikes priced across the remaining meetings of 2026. The October meeting carries a 55% probability of action (+13.8bps implied), with December at 77% (+33bps implied). The FOMC statement noted that “today’s policy action will support a timelier return to the committee’s 2% goal”. The Fed’s preferred inflation gauge, PCE, stood at 3.7% year-on-year as of July 2026 – well above the 2% target – while August core CPI printed at 0.3% month-on-month (2.4% year-on-year), which is also above expectations. This reinforces the case for continued tightening. With the US economy in robust health, driven by significant AI-related capital expenditure, there is little in the near-term data to deter the Fed from acting further.
Europe shows a similar pattern: the European Central Bank (ECB) deposit rate currently stands at 2.5%, having been set at the 10 September meeting. OIS markets now price the ECB deposit rate climbing to 2.8% by the December meeting – a move of approximately 36bps from the current level. The October meeting carries a 55% probability of action, and December carries an 89% probability. This synchronised tightening across the two largest developed-market central banks marks a clear shift from the easing narrative that dominated much of 2025, with important consequences for the pricing of interest rate risk.
The macro backdrop reinforces the concern. Inflation remains sticky, labour markets resilient, and fiscal deficits continue to add duration to the market. US national debt has passed $40 trillion – double its level a decade ago – increasing the cost of servicing borrowing as rates rise (Figure 1). This is not only a US issue: developed-market governments have accumulated substantial debt since the global financial crisis, while political uncertainty in the UK, France and elsewhere has refocused attention on strained debt trajectories. The UK budget on 28 October and the US mid-term elections in early November potentially complicate things further.
Figure 1: US Federal debt
US Federal debt ($ trillions)
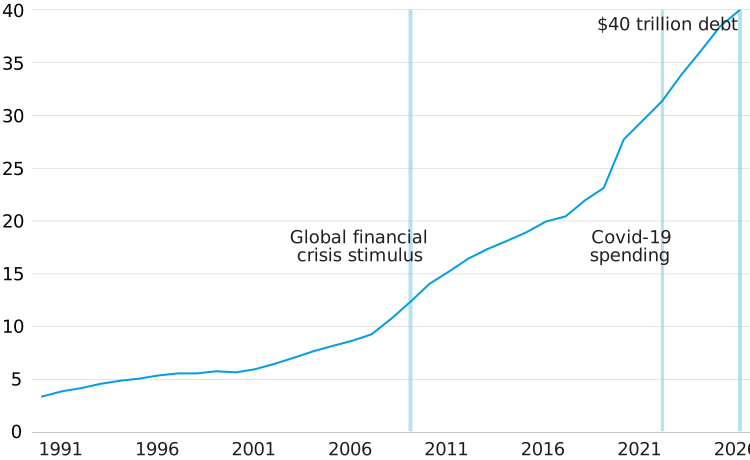
Source: Bloomberg, August 2026
Geopolitical risk is amplifying the inflation outlook
A critical driver of the current rate environment is the conflict in the Middle East. The situation has deteriorated, with both the US and Iran claiming control of the Strait of Hormuz and visible shipping through the waterway extremely low. Oil exports from the region are estimated to have recovered to around two-thirds of pre-war levels through dark transits and pipeline capacity, but Brent Crude remains elevated and stress persists in refined products such as diesel and in liquified natural gas markets, where pipeline alternatives are limited. With no negotiations under way and a resolution before the US mid-term elections unlikely, the conflict could remain a source of commodity price pressure and inflation uncertainty through to the end of the year.
That geopolitical pressure feeds directly into the rate outlook. Higher commodity prices sustain inflation, reinforcing the case for tighter policy. At Columbia Threadneedle Investments, our macro outlook factors the oil price jump into a higher inflation profile into year-end 2026, while deglobalisation and fiscal laxity across the G7 add structural upward pressure. With geopolitical risk, sticky inflation and a hawkish Fed all in play, the conditions for market turbulence are clearly present.
Rate volatility has structurally repriced
The ICE BofA MOVE Index, which measures expected volatility in US Treasuries, reached a 2026 high of 115 in late March before falling to around 72 by late August, with a year-to-date average of about 72.9 – still well above January lows of 56 (Figure 2). This points to a structural repricing of rate uncertainty, not a temporary spike. Even after the US Treasury increased its buyback programme for longer-dated bonds in mid-August, yields moved back above pre-announcement levels, underlining the limits of demand-side support when inflation is persistent and central banks remain hawkish. Elevated rate volatility means wider bid-offer spreads, higher hedging costs and greater mark-to-market volatility for longer-dated bonds.
Figure 2: A structural repricing of rate uncertainty
ICE BofA Move index (US Treasury market volatility)
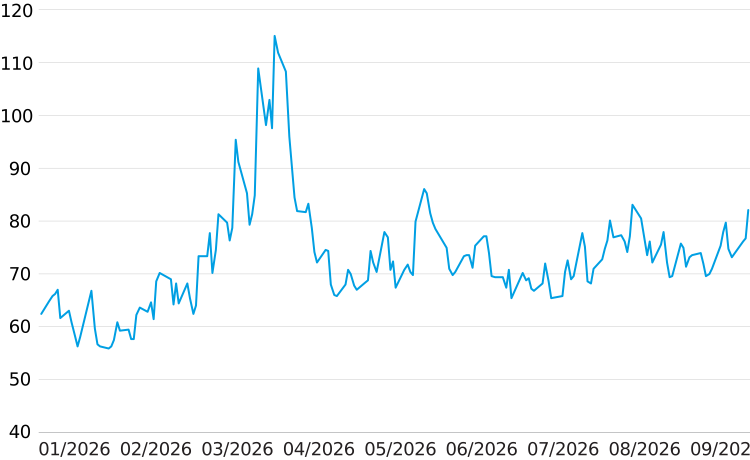
Source: Bloomberg, 17 September 2026
The risks remain asymmetric. For long-duration bond holders, the price impact of a further 50bps rise in yields on a 10-year instrument is materially larger than the gain from an equivalent rally. Convexity works against investors in a rising-rate, high-volatility regime, while carry offers limited compensation. The lesson of 2022, when many investors were overexposed to duration, remains highly relevant.
The CT (Lux) European Short-Term High Yield Bond
In this environment, Columbia Threadneedle’s CT (Lux) European Short-Term High Yield Bond, managed by Gareth Simmons and David Backhouse, is designed for these conditions. The Fund has an effective duration of 1.8 years, a yield to maturity of 4.95% and a yield to worst of 4.6%.1 This mix of income and low duration provides a buffer against rate volatility: yields would need to rise by around 260 bps before the Fund lost money over a 12-month horizon – a margin of safety that is hard to replicate in longer-duration alternatives.
A key differentiator is the Fund’s use of legal maturity constraints, not duration targets alone. At least 80% of assets must be held in bonds with a legal maturity of four years or less. This helps avoid the negative convexity risk found in callable bond-heavy strategies, where duration can extend precisely when markets sell off, providing a more consistent risk profile through the cycle. The Fund’s credit quality also supports its defensive positioning: 63.4% of the portfolio is rated BB, with CCC exposure capped at 2.2%. Columbia Threadneedle’s 12-month default forecast for European high yield universe is 2.7%, with defaults concentrated in CCC-rated issuers – the segment the Fund limits by design.
A proven process and track record built for volatile markets
The Fund is backed by a global high yield team of 29 investment professionals managing $19 billion in leveraged credit assets, with portfolio managers averaging 24 years of industry experience.
The process combines bottom-up credit research with a disciplined top-down framework that adjusts risk positioning according to the macro backdrop, default outlook, technicals and valuations. Environmental, social and governance integration is embedded throughout, and the Fund is Article 8 under SFDR, with carbon intensity meaningfully below its reference index.
Since inception in July 2019, the Fund has shown an ability to limit drawdowns and recover quickly in risk-off markets. Its 2022 calendar-year loss of -4.3% compared with -6% for the reference index, illustrates the value of its duration framework in a rising-rate environment (see GIPs Report below). The Fund then delivered a gross return of +10.6% in 2023 and, over five years, ranks in the first quartile of its short-term high yield peer group for both net return and Sharpe ratio.
Conclusion: Fasten your seatbelts – but stay invested
History shows that financial markets often hit an air pocket when the Fed raises rates – and with the autumn bringing a confluence of geopolitical risk, sticky inflation, central bank tightening, political uncertainty and elevated rate volatility, the question of whether to fasten seatbelts is increasingly pertinent. For investors seeking to remain invested while reducing their exposure to the primary source of near-term risk – duration repricing – the CT (Lux) European Short-Term High Yield Bond can offer a structurally sound and well-evidenced solution. High income, low duration, disciplined credit selection and a proven ability to preserve capital through volatile markets make it a compelling allocation for the environment ahead.
Recent positioning reflects this conviction in practice. Over the summer, the team increased exposure to AI data centre-related credits, where current valuations, held back by a substantial supply pipeline, are viewed as increasingly attractive against a backdrop of structurally growing demand for compute infrastructure. Exposure to gaming credits was also added, where valuations had lagged the broader market recovery, with the sector offering resilient cash generation underpinned by well-structured balance sheets.
Corporate fundamentals remain solid heading into the autumn, with the team’s latest bottom-up analysis projecting European high yield default rates of 2.7% over the next 12 months and 4.7% on a cumulative 24-month basis – both below long-run averages. Credit spreads continue to sit in the tightest decile relative to history, reinforcing the case for carry-focused strategies and limiting reliance on further spread compression to drive returns. Should a pullback occur, the team expects it to be shallow given the strong fundamental backdrop, and the Fund remains positioned to capitalise on any volatility that does emerge.
Unless stated, all data is Bloomberg as of 17 September 2026.
Columbia Threadneedle European Short-Term High Yield Composite - GIPS Report
Columbia Threadneedle Investments Global Asset Management
Reporting Currency: EUR
Statement of Performance Results
Cal. Year | Gross-of-fees Return (%) | Net-of-fees Return (%) | Index Return (%) | Composite 3-Yr St Dev (%) | Index 3-Yr St Dev (%) | Internal Dispersion (%) | Number of Portfolios | Total Composite Assets (mil.) | Total Firm Assets (bil.) |
|---|---|---|---|---|---|---|---|---|---|
2025 | 4.53 | 4.02 | 5.49 | 1.95 | 1.92 | N/A | ≤ 5 | 135.1 | 498.44 |
2024 | 6.81 | 6.28 | 6.63 | 4.84 | 4.71 | N/A | ≤ 5 | 103.2 | 535.24 |
2023 | 10.63 | 10.08 | 10.34 | 4.84 | 4.69 | N/A | ≤ 5 | 70.3 | N/A |
2022 | -4.27 | -4.75 | -5.97 | 7.30 | 8.90 | N/A | ≤ 5 | 85.7 | N/A |
2021 | 2.71 | 2.20 | 3.23 | N/A | N/A | N/A | ≤ 5 | 110.9 | N/A |
2020 | 2.73 | 2.22 | 0.62 | N/A | N/A | N/A | ≤ 5 | 77.7 | N/A |
2019* | 1.03 | 0.82 | 1.48 | N/A | N/A | N/A | ≤ 5 | 54.2 | N/A |
*For the period 31/07/2019 through 31/12/2019
Annualised Trailing Performance as of December 31 2025
Period | Gross-of-fees Return (%) | Net-of-fees Return (%) | Index Return (%) |
|---|---|---|---|
1 Year | 4.53 | 4.02 | 5.49 |
5 Years | 3.96 | 3.45 | 3.80 |
Inception | 3.67 | 3.16 | 3.28 |
Inception Date: July 31 2019
- Columbia Threadneedle Investments Global Asset Management claims compliance with the Global Investment Performance Standards (GIPS®) and has prepared and presented this report in compliance with the GIPS standards. Columbia Threadneedle Investments Global Asset Management has been independently verified for the periods of January 1, 1993 to December 31, 2024. The verification report is available upon request. A firm that claims compliance with the GIPS standards must establish policies and procedures for complying with all the applicable requirements of the GIPS standards. Verification provides assurance on whether the firm’s policies and procedures related to composite and pooled fund maintenance, as well as the calculation, presentation, and distribution of performance, have been designed in compliance with the GIPS standards and have been implemented on a firm-wide basis. Verification does not provide assurance on the accuracy of any specific performance report. GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein.
- The Firm is defined as Columbia Threadneedle Investments Global Asset Management (formerly known as Columbia Threadneedle Investments North America prior to June 30, 2024). The Firm provides a broad range of investment management and related services to individual, institutional, and corporate clients around the world. Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. The Firm was redefined on June 30, 2024, to include the GIPS firms of Columbia Management Capital Advisers, Columbia Threadneedle Investments EMEA APAC, and Columbia Threadneedle (EM) Investments Limited. The Columbia Management Capital Advisers firm offered investment management and related services to clients participating in various types of wrap programs. The Columbia Threadneedle Investments EMEA APAC firm consisted of all portfolios managed by various Threadneedle group companies. The Columbia Threadneedle (EM) Investments Limited firm was a subsidiary of Columbia Threadneedle Investments International Limited, which defined a portion of its business specializing in Global Emerging Markets equities. As of November 1, 2020, the Firm was redefined to include Columbia Cent CLO Advisers, LLC. As of January 1, 2017, the Firm was redefined to include Columbia Wanger Asset Management, LLC, a wholly-owned subsidiary of Columbia Management Investment Advisers, LLC. Beginning March 30, 2015, the Columbia and Threadneedle group of companies, which includes multiple separate and distinct GIPS-compliant firms, began using the global offering brand Columbia Threadneedle Investments. The Firm includes accounts managed by various Columbia Threadneedle Investments entities, including Columbia Management Investment Advisers, LLC, Threadneedle Asset Management Limited, Threadneedle Investments Singapore (Pte.) Limited, Threadneedle Management Luxembourg S.A., and other affiliated entities.
- The strategy will seek exposure, directly or indirectly, to credit rated below Investment Grade, that is issued by companies domiciled in Europe or with significant European operations, or is denominated in EUR or GBP. A minimum of 80% of investments will be less or equal to 4 years of maturity. Derivative instruments may be used for efficient portfolio management and currency management. The primary use of derivatives is not designed to create a highly leveraged investment position. The composite was created July 31, 2019.
- The gross-of-fees returns are time-weighted rates of return net of commissions and other transaction costs. Net-of-fees returns are calculated by deducting from the monthly gross-of-fees composite return one-twelfth of the highest client fee (model fee) in effect for the respective period. Composite returns reflect the reinvestment of dividends and other earnings.
- Internal dispersion is calculated using the equal-weighted standard deviation of the annual gross returns of those portfolios that were included in the Composite for the entire year. If the composite contains five or fewer accounts for the full year, a measure of dispersion is not statistically representative and is therefore not shown.
- The three-year annualized standard deviation measures the variability of the gross-of-fees composite and benchmark returns over the preceding 36-month period. It is not required to be presented when a full three years of performance is not yet available.
- Returns are calculated net of non-reclaimable withholding taxes on dividends, interest, and capital gains. Policies for valuing investments, calculating performance, and preparing GIPS Reports, as well as the list of composite descriptions, list of pooled fund descriptions for limited distribution pooled funds, and the list of broad distribution pooled funds are available upon request.
- The following fee schedule represents the current representative fee schedule used as the starting point for fee negotiations for institutional clients seeking investment management services in the designated strategy: 0.5% on the first £50m; 0.4% on the next £50m; negotiable thereafter. Gross of fee performance information does not reflect the deduction of management fees. The following statement demonstrates, with a hypothetical example, the compound effect fees have on investment return: If a portfolio’s annual rate of return is 5% for 5 years and the annual management fee is 50 basis points, the gross total 5-year return would be 27.6% and the 5-year return net of fees would be 24.5%.
- The ICE BofA 0-4yrs European Currency High Yield, BB-B, 3% constrained, excluding Subordinates is a custom Index that uses stocks from the ICE BofA European High Yield Index that have a maturity of no more that 4 years, a rating of BB-B and excludes Subordinates. The index is hedged 100% into Euro’s. Index returns reflect the reinvestment of dividends and other earnings and are not covered by the report of the independent verifiers.
- Past performance is no guarantee of future results and there is the possibility of loss of value. There can be no assurance that an investment objective will be met or that return expectations will be achieved. Care should be used when comparing these results to those published by other investment advisers, other investment vehicles and unmanaged indices due to possible differences in calculation methods.
- This composite was included in the Columbia Threadneedle Investments EMEA APAC GIPS firm prior to joining the Columbia Threadneedle Investments Global Asset Management GIPS firm on 6/30/2024. As the composite was not part of Columbia Threadneedle Investments Global Asset Management prior to 6/30/2024, firm assets are shown as “N/A” in the performance table.