at
AT
Austria
de-AT
at_intm_classes
intm
Intermediary
de
de
For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients).
Zoomed in microchip on a colourful motherboard

Insights

Data with destiny: Information services show structural resilience in the age of AI

Arabella Duckworth
Investment Grade Credit Research, Fixed Income

Disruption fears look overdone – trusted data, regulation and embedded workflows should continue to support resilient information services credits.

Generative and agentic artificial intelligence (AI) has been treated as an existential threat to established information services (IS) companies. We believe that risk is over-discounted. For issuers that own proprietary content, operate in regulated markets and sit inside mission-critical workflows, AI is more likely to improve products, extend distribution and support margins than destroy the franchise. The key distinction is between businesses that control trusted data and accountable outcomes, and those that provide a replaceable interface.

Equity valuations have absorbed more disruption risk than current credit fundamentals appear to justify. Bond market reactions have been more measured: stable earnings, strong cash generation and generally conservative balance sheets have limited fundamental stress, although longer-dated bonds remain more exposed to uncertainty around the terminal value of data and workflow franchises.

Figure 1: Strong balance sheets supported by consistent financial policies can absorb the impact of potential tech-related AI changes

IS companies’ current market cap and net adjusted leverage
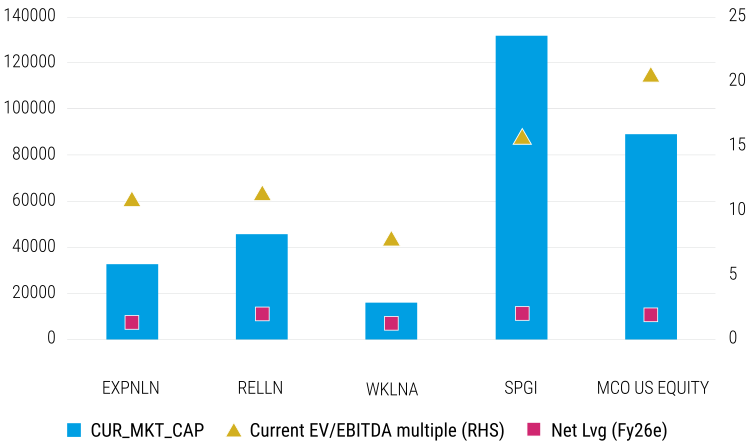
Figure 1: Strong balance sheets supported by consistent financial policies can absorb the impact of potential tech-related AI changes

Source: Bloomberg and analysis of company reports, 4 September 2026

Modest spread moves do not make the sector an automatic overweight. Starting valuations have been tight and shareholder distributions have risen at several issuers, so AI is best viewed as a source of issuer and curve dispersion rather than near-term rating upside. Within IS, Experian1 remains our preferred risk-reward opportunity: its hard-to-replicate credit data, identity capabilities and regulated use cases support a durable single-A profile, while the market response to its less subscription-led revenue mix looks overly cautious.

Figure 2: Spreads over 12 months have outperformed the index with underperformance modest YTD

OAS spreads of comparative IS € issuers compared to the € IG index
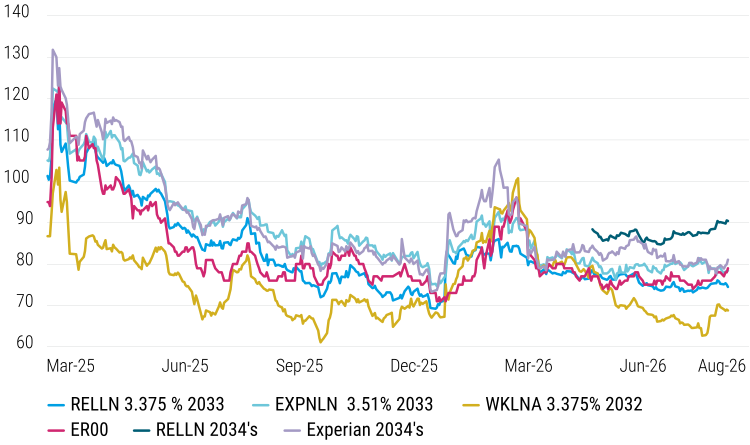
Figure 2: Spreads over 12 months have outperformed the index with underperformance modest YTD

Source: Bloomberg, August 2026

Why the strongest businesses should remain resilient

1. Proprietary data ownership and quality

AI raises the value of clean, current and authoritative data because model output is only as reliable as the information on which it is grounded. IS companies have spent decades collecting, validating and enriching datasets that are difficult to replicate. Customers pay for accuracy, auditability, permissioning and expert curation. Recent results support this thesis: Experian reported 8% organic growth in FY26 and nearly $2 billion of revenue from new and scaling products2 ; RELX reported 7% underlying revenue growth and 9% underlying adjusted operating-profit growth in H1 20263 ; and Moody’s Q2 2026 revenue rose 15%, with Moody’s Analytics annualised recurring revenue up 9%.4

2. Business quality supports credit quality

Leading issuers typically combine recurring revenue, high renewal rates, strong margins and robust free cash flow. These traits matter because AI adoption requires sustained investment in cloud infrastructure, data engineering, model governance, cybersecurity and specialist talent. Scale lets incumbents fund that investment while protecting debt service and strategic flexibility.  Strong cash flow generation and balance-sheet headroom help absorb higher technology spending and operational costs and, in a worst-case scenario, can manage operational incidents and associated costs. Smaller competitors face a tougher trade-off: underinvest and risk product erosion, or invest heavily and potentially weaken leverage and ratings.

3. Regulatory protection, accreditation and accountability

Rating agencies and credit bureaux operate in markets where regulation, accreditation and institutional trust create formidable barriers to entry. In high-stakes applications such as ratings, lending, legal research, tax, healthcare and compliance, customers require transparent methodologies, explainable decisions, permissioned data and an accountable provider. General-purpose models can improve the user experience, but they do not automatically inherit regulatory status, contractual liability or customer trust.

4. Mission-critical workflow entrenchment

The strongest platforms are embedded in customer processes rather than used as stand-alone databases. Their data feeds, analytics, decision rules and audit trails sit inside legal, financial, clinical and corporate systems, making replacement costly and risky. AI may change the interface, but the more likely base case is broader use of incumbent data and decision infrastructure, not wholesale displacement.

What could go wrong?

Agentic AI could move further up the workflow stack. Autonomous tools could execute complex tasks across multiple data sources at lower cost, reducing the value of incumbent interfaces. The risk is greatest where products support low-complexity decisions, rely on widely available information or have limited switching costs. Workflow-heavy providers such as Wolters Kluwer are more exposed than businesses whose moat rests on proprietary data, regulated status or authoritative content.

Cyber/data risks and reputational damage could overwhelm the benefit. More connected platforms, third-party models and cloud infrastructure expand the attack surface. For data-rich companies, a major breach could bring remediation costs, litigation, regulatory penalties, weaker new-business wins and lasting reputational damage. This is the most credible route from an AI-related event to material spread widening or rating pressure.

Execution and capital allocation could disappoint. Incumbents may underinvest, choose the wrong partners, fail to protect intellectual property or spend heavily without achieving adoption. Management teams could also respond to equity-market pressure with larger buybacks, debt-funded acquisitions or expensive AI capability purchases. RELX, for example, reported a £2.25 billion 2026 buyback programme given its low leverage (H1 2026 2.3x). These risks remain manageable while financial policies are disciplined, but can erode the balance-sheet advantage underpinning the credit case.

The bottom line: Implications for Investment Grade bonds

IS should be viewed as selective AI winners at the margin, not a uniform set of disruption losers. AI makes trusted, governable and workflow-ready data more valuable. The best-positioned incumbents own proprietary content, operate under meaningful regulation, deliver accountable outcomes and retain the capacity to invest. Credit investors should focus on who owns the data, who carries the liability, how deeply the product is embedded, and whether the balance sheet can withstand execution, cyber and capital-allocation shocks.

Within investment grade bonds, AI is more likely to create issuer dispersion and episodic volatility than broad-based fundamental deterioration. Stronger credits should benefit from recurring cash flow, margin resilience and manageable leverage, but tight spreads limit broad upside. Headline-driven selloffs can create opportunities where a severe disruption scenario is not visible in operating performance.

We view most sector valuations as broadly fair, with Experian offering the better risk-reward because its difficult-to-replicate datasets and trust and accountability requirements make it more likely to be an AI enabler than a casualty. The principal downside risk remains a major cyber incident, but we view this as a tail risk that would be workable for a strong active management team.
Hauptthemen

Abonnieren Sie Insights

Optimieren Sie unsere auf Sie zugeschnittene E-Mail, indem Sie die Arten von Insights und Informationen, die Sie von uns erhalten möchten, individuell anpassen.

Aktuelle Beiträge

Disruption fears look overdone – trusted data, regulation and embedded workflows should continue to support resilient information services credits.
The spread between French and German government debt has once again breached 100bps, reflecting a confluence of French fiscal and political pressures.
After a series of policy meetings across the major central banks, the direction of travel for interest rates remains finely balanced.
Hauptthemen
Verwandte Themen

1 Mention of specific stocks is not a recommendation to buy or sell
2 Experian, FY26 results and AI-enabled growth update, 19 May 2026
3 RELX, first-half 2026 results, 23 July 2026
4 Moody’s, Second-quarter 2026 results, 22 July 2026

Important information

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients). For marketing purposes.

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk.  Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414.  TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act 2001 (Cth) and relies on Class Order 03/1102 in respect of the financial services it provides to wholesale clients in Australia. This document should only be distributed in Australia to “wholesale clients” as defined in Section 761G of the Corporations Act.  TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Investment Management Association of Japan and Type II Financial Instruments Firms Association.

In the UK: Issued by Threadneedle Asset Management Limited, No. 573204 and/or Columbia Threadneedle Management Limited, No. 517895, both registered in England and Wales and authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A., registered with the Registre de Commerce et des Sociétés (Luxembourg), No. B 110242 and/or Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

In the Middle East: This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA).  For Distributors: This document is intended to provide distributors with information about Group products and services and is not for further distribution. For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

This document may be made available to you by an affiliated company which is part of the Columbia Threadneedle Investments group of companies: Columbia Threadneedle Management Limited in the UK; Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. © 2026 Columbia Threadneedle. All rights reserved.

Verwandte Beiträge

22 September 2026

In Credit Weekly Snapshot – Encore une fois

The spread between French and German government debt has once again breached 100bps, reflecting a confluence of French fiscal and political pressures.
17 September 2026

Senior Portfolio Manager, Investment Grade Credit

Hyperscaler debt issuance: A technical opportunity in investment grade credit

AI hyperscalers are reshaping the IG credit market, creating attractive dislocations in fundamentally strong issuers – and an attractive entry point.
15 September 2026

In Credit Weekly Snapshot – No more zeros

With average interest rates of 14.7% over the past four millennia, and 4.7% over the past 400 years, the real anomaly was the zero-rate period of the 2000s.
22 September 2026

In Credit Weekly Snapshot – Encore une fois

The spread between French and German government debt has once again breached 100bps, reflecting a confluence of French fiscal and political pressures.
21 September 2026

Senior Economist, Multi-Asset Solutions team

Market Perspectives: The roadmap for central banks

After a series of policy meetings across the major central banks, the direction of travel for interest rates remains finely balanced.
17 September 2026

Senior Portfolio Manager, Investment Grade Credit

Hyperscaler debt issuance: A technical opportunity in investment grade credit

AI hyperscalers are reshaping the IG credit market, creating attractive dislocations in fundamentally strong issuers – and an attractive entry point.

Important information

For use by professional clients and/or equivalent investor types in your jurisdiction (not to be used with or passed on to retail clients). For marketing purposes.

This document is intended for informational purposes only and should not be considered representative of any particular investment. This should not be considered an offer or solicitation to buy or sell any securities or other financial instruments, or to provide investment advice or services. Investing involves risk including the risk of loss of principal. Your capital is at risk.  Market risk may affect a single issuer, sector of the economy, industry or the market as a whole. The value of investments is not guaranteed, and therefore an investor may not get back the amount invested. International investing involves certain risks and volatility due to potential political, economic or currency fluctuations and different financial and accounting standards. The securities included herein are for illustrative purposes only, subject to change and should not be construed as a recommendation to buy or sell. Securities discussed may or may not prove profitable. The views expressed are as of the date given, may change as market or other conditions change and may differ from views expressed by other Columbia Threadneedle Investments (Columbia Threadneedle) associates or affiliates. Actual investments or investment decisions made by Columbia Threadneedle and its affiliates, whether for its own account or on behalf of clients, may not necessarily reflect the views expressed. This information is not intended to provide investment advice and does not take into consideration individual investor circumstances. Investment decisions should always be made based on an investor’s specific financial needs, objectives, goals, time horizon and risk tolerance. Asset classes described may not be suitable for all investors. Past performance does not guarantee future results, and no forecast should be considered a guarantee either. Information and opinions provided by third parties have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. This document and its contents have not been reviewed by any regulatory authority.

In Australia: Issued by Threadneedle Investments Singapore (Pte.) Limited [“TIS”], ARBN 600 027 414.  TIS is exempt from the requirement to hold an Australian financial services licence under the Corporations Act 2001 (Cth) and relies on Class Order 03/1102 in respect of the financial services it provides to wholesale clients in Australia. This document should only be distributed in Australia to “wholesale clients” as defined in Section 761G of the Corporations Act.  TIS is regulated in Singapore (Registration number: 201101559W) by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289), which differ from Australian laws.

In Singapore: Issued by Threadneedle Investments Singapore (Pte.) Limited, 3 Killiney Road, #07-07, Winsland House 1, Singapore 239519, which is regulated in Singapore by the Monetary Authority of Singapore under the Securities and Futures Act (Chapter 289). Registration number: 201101559W. This advertisement has not been reviewed by the Monetary Authority of Singapore.

In Hong Kong: Issued by Threadneedle Portfolio Services Hong Kong Limited 天利投資管理香港有限公司. Unit 3004, Two Exchange Square, 8 Connaught Place, Hong Kong, which is licensed by the Securities and Futures Commission (“SFC”) to conduct Type 1 regulated activities (CE:AQA779). Registered in Hong Kong under the Companies Ordinance (Chapter 622), No. 1173058.

In Japan: Issued by Columbia Threadneedle Investments Japan Co., Ltd. Financial Instruments Business Operator, The Director-General of Kanto Local Finance Bureau (FIBO) No.3281, and a member of Investment Management Association of Japan and Type II Financial Instruments Firms Association.

In the UK: Issued by Threadneedle Asset Management Limited, No. 573204 and/or Columbia Threadneedle Management Limited, No. 517895, both registered in England and Wales and authorised and regulated in the UK by the Financial Conduct Authority.

In the EEA: Issued by Threadneedle Management Luxembourg S.A., registered with the Registre de Commerce et des Sociétés (Luxembourg), No. B 110242 and/or Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

In Switzerland: Issued by Threadneedle Portfolio Services AG, Registered address: Claridenstrasse 41, 8002 Zurich, Switzerland.

In the Middle East: This document is distributed by Columbia Threadneedle Investments (ME) Limited, which is regulated by the Dubai Financial Services Authority (DFSA).  For Distributors: This document is intended to provide distributors with information about Group products and services and is not for further distribution. For Institutional Clients: The information in this document is not intended as financial advice and is only intended for persons with appropriate investment knowledge and who meet the regulatory criteria to be classified as a Professional Client or Market Counterparties and no other Person should act upon it.

This document may be made available to you by an affiliated company which is part of the Columbia Threadneedle Investments group of companies: Columbia Threadneedle Management Limited in the UK; Columbia Threadneedle Netherlands B.V., regulated by the Dutch Authority for the Financial Markets (AFM), registered No. 08068841.

Columbia Threadneedle Investments is the global brand name of the Columbia and Threadneedle group of companies. © 2026 Columbia Threadneedle. All rights reserved.

Icon checked

Vielen Dank. Sie können jetzt Ihr Präferenzzentrum besuchen, um auszuwählen, welche Insights Sie per E-Mail erhalten möchten.

Icon checked

Vielen Dank. Sie können jetzt Ihr Präferenzzentrum besuchen, um auszuwählen, welche Insights Sie per E-Mail erhalten möchten.

Icon checked

Vielen Dank. Sie können jetzt Ihr Präferenzzentrum besuchen, um auszuwählen, welche Insights Sie per E-Mail erhalten möchten.

Bitte bestätigen Sie einige Angaben zu Ihrer Person, um Ihr Präferenzzentrum zu besuchen

*Pflichtfelder

Etwas ist schiefgelaufen, bitte versuchen Sie es erneut

Vielen Dank. Sie können jetzt Ihr Präferenzzentrum besuchen, um auszuwählen, welche Einblicke Sie per E-Mail erhalten möchten.

Um zu sehen und zu aktualisieren, welche Erkenntnisse Sie von uns per E-Mail erhalten, besuchen Sie bitte Ihr Preference Center.